Etihad Credit Bureau has launched Credit Score 3i, an upgraded individual credit scoring model that extends the assessment period from 24 to 36 months and introduces scoring for people with limited credit histories in the UAE.
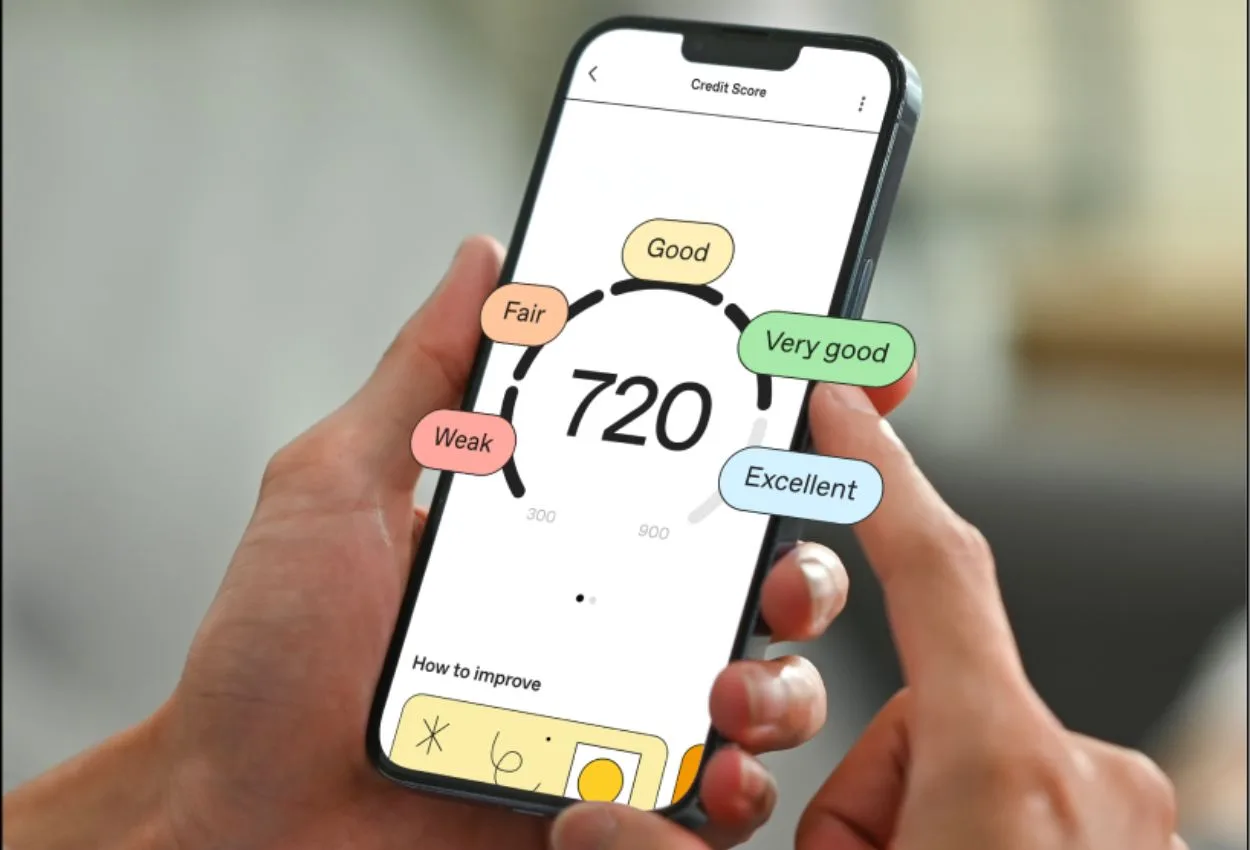
The federal bureau unveiled the model at its new Abu Dhabi office. Two distinct scoring ranges now apply depending on a customer’s credit history: 300 to 850 for individuals with established records, and 300 to 650 for those new to credit or recently arrived in the country. Previously, no score was available to individuals in that second category.
“The UAE continues to develop its financial and credit information ecosystem in step with economic and technological change. Credit Score 3i advances the use of data and analytics to support more comprehensive credit risk assessments, strengthen financial sector efficiency and encourage responsible credit practices. The new model provides deeper insights into individuals’ credit behaviour over longer periods and extends credit scoring to additional eligible segments. It introduces two scoring ranges: 300–850 for individuals with established credit histories and 300–650 for eligible individuals with limited credit histories. This helps individuals better understand their credit profiles and supports lenders in making informed decisions and managing risk more effectively,” Marwan Ahmad Lutfi, Director General of Etihad Credit Bureau said in a statement.
“The new model analyses positive practices, recognises sustained improvements in credit behaviour, and reflects these improvements in the score within six months after defaults have been settled. Through the credit report, it also provides an analysis of the factors influencing the score, whether positive or negative, and offers users a number of recommendations that may help improve their score if followed. These updates help individuals gain a clearer understanding of their credit profiles, enabling them to make responsible financial decisions and adopt positive financial behaviours,” he added.
One practical change is the pace at which recovered borrowers can see their scores improve. Following the resolution of a default, consistent repayment behaviour may be reflected in a higher score within six months. The bureau was careful to note this is not guaranteed and depends on subsequent behaviour and the model’s criteria.
The model also provides borrowers with a breakdown of the factors affecting their score, both positive and negative, along with recommendations. For lenders and authorised entities, including eligible fintech companies, the wider dataset is intended to support more granular risk assessments.
The launch comes as the UAE’s credit ecosystem has grown substantially. As of September 2026, the bureau’s active database covered roughly 11.6 million individuals and businesses, 20.2 million active credit contracts, and 25.3 million active IBANs. Credit reports and scores issued annually have risen from around one million in 2015 to more than 17 million in 2025.
Earlier in 2026, the bureau also expanded its reporting scope to include Buy Now, Pay Later accounts and other short-term credit products, capturing a category of financial obligation that had previously sat outside formal credit reporting.
Individuals can access their credit score through the bureau’s website or its mobile app on iOS and Android.